

Riyadh Cement CEO: Selling prices fluctuate on competition, demand to rebound slowly

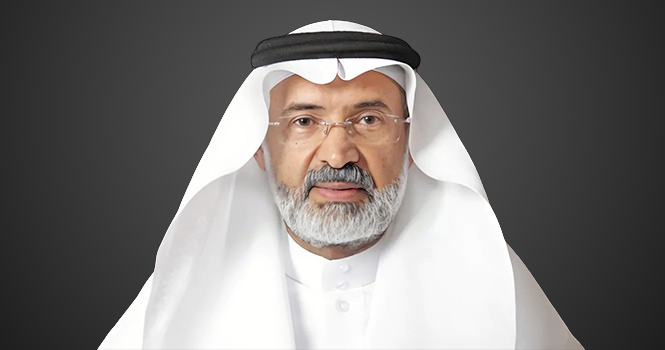
Riyadh Cement CEO Shoeil Al Ayed says the company has no bank liabilities, which provides financial flexibility to support its operational and investment plans.
Riyadh Cement Co.’s CEO Shoeil Al Ayed said selling prices continue to fluctuate due to ongoing price competition, particularly in the Central Province, while demand levels remained stable in H1 2026 compared to the same period last year.
He told Argaam that the market is currently experiencing a relative oversupply, driven by higher clinker production at a number of companies.
The company is addressing these conditions through operational and commercial discipline by aligning production with actual demand, efficiently managing inventory levels, maintaining sustainable profit margins, and focusing on higher-margin products, mainly white cement.
He expects cement demand to improve gradually during the second half of 2026, supported by continued government spending, accelerated project execution and improved private-sector activity.
This improvement is expected to positively impact sales volumes, alongside a gradual recovery in market stability, which will support Riyadh Cement’s financial and operational performance. The company will continue to maintain its focus on operational efficiency and maximizing shareholder returns, Al Ayed stated.
The CEO disclosed that the average selling price of black cement reached approximately SAR 176 per ton during Q2 2026, affected by continued pricing pressures resulting from oversupply and high clinker inventories across the sector.
Meanwhile, total clinker inventories across the sector reached almost 45 million tons by the end of Q2 2026, while the company's clinker inventory stood at nearly 1.4 million tons. This level is in line with the company's strategy to ensure readiness to meet expected demand, maintain continuity of operations, and strike a balance between production and inventory levels in line with market developments and the company's long-term plans, Al-Ayed stated.
He explained that the Q2 2026 profit margin was affected by approximately 4 percentage points due to higher fuel prices, which were the main factor behind the increase in the cost of sales during the period.
Despite this impact, Riyadh Cement was able to limit its effect on its financial results by improving operational efficiency, managing costs, and increasing the contribution of white cement to sales, which helped maintain good profitability levels compared with market conditions.
Based on current conditions, the cement producer expects fuel costs to remain stable during the second half of 2026, unless there are significant changes in energy prices or other operational factors, he noted.
The CEO further stated that Riyadh Cement continues to benefit from its strong financial position and without any bank liabilities, providing financial flexibility to support its operational and investment plans, enhance its ability to withstand market fluctuations, and capitalize on future growth opportunities.
Regarding the impact of geopolitical developments, Al-Ayed said their effect on the company's operations was “limited”, mainly taking the form of higher costs and slower delivery of certain imported spare parts.
“This did not have a material impact on the continuity of our operations, thanks to efficient supply chain management and procurement planning. We were not materially affected by raw material and fuel costs, given our reliance on local sources for more than 99% of our raw material requirements, in addition to stable fuel supplies within Saudi Arabia,” said the CEO.
He added that clinker exports across the sector have been impacted since the beginning of 2026 due to logistical challenges associated with regional developments. However, this did not have a material impact on the company's performance, given its primary reliance on the domestic market for selling black and white cement.
According to data available with Argaam, Riyadh Cement's net profit declined to SAR 110 million in H1 2026, down 17% from SAR 133 million a year ago.

Market Indices
Quotes
About Us
Join Us

Comments {{getCommentCount()}}
Be the first to comment
رد{{comment.DisplayName}} على {{getCommenterName(comment.ParentThreadID)}}
{{comment.DisplayName}}
{{comment.ElapsedTime}}